The post Why Startups Prefer Private Limited Companies in India first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>This decision matters more than most founders realize.
The business structure you choose can affect fundraising opportunities, legal protection, taxation, ownership flexibility, compliance requirements, and even how investors or clients view your company in the future.
That is one of the main reasons why most startups in India prefer registering as a Private Limited Company. From raising investment to building credibility and scaling operations, this structure offers advantages that align well with long-term startup growth.
In this guide, we will understand why startups prefer Private Limited Companies, how this structure supports business expansion, and when it may or may not be the right choice for your startup.
What is a Private Limited Company?
A Private Limited Company is a legally registered business entity that operates separately from its owners. In simple words, the company has its own legal identity.
This means:
- the company can own assets,
- enter contracts,
- raise funding,
- and continue operating independently of the founders.
A Private Limited Company generally includes:
- shareholders,
- directors,
- and equity ownership through shares.
One of the biggest reasons startups choose this structure is limited liability protection. The personal assets of founders are usually protected if the business faces losses or financial challenges.
For startups planning long-term growth, fundraising, or expansion, a Private Limited Company often becomes the preferred option.
Businesses looking for professional startup incorporation support often explore Company & Business Registration Services to understand the registration process and compliance requirements properly.
Why Choosing the Right Business Structure Matters for Startups
Many founders focus heavily on product development, hiring, and customer acquisition in the early stage. However, the business structure selected during incorporation can directly influence the future of the startup.
A wrong structure can create challenges later in:
- fundraising,
- ownership transfer,
- investor onboarding,
- taxation,
- compliance,
- and scalability.
For example, some startups initially choose an LLP because compliance requirements seem simpler. But later, when they approach investors, they realize that many angel investors and venture capital firms prefer investing in Private Limited Companies.
Similarly, ownership restructuring and ESOP planning become easier under a Private Limited structure.
This is why founders should think beyond short-term registration costs and consider long-term business goals before deciding the structure.
Startups that need guidance regarding business planning, scalability, and operational structure often seek help from Business & Corporate Advisory Service to make better strategic decisions from the beginning.
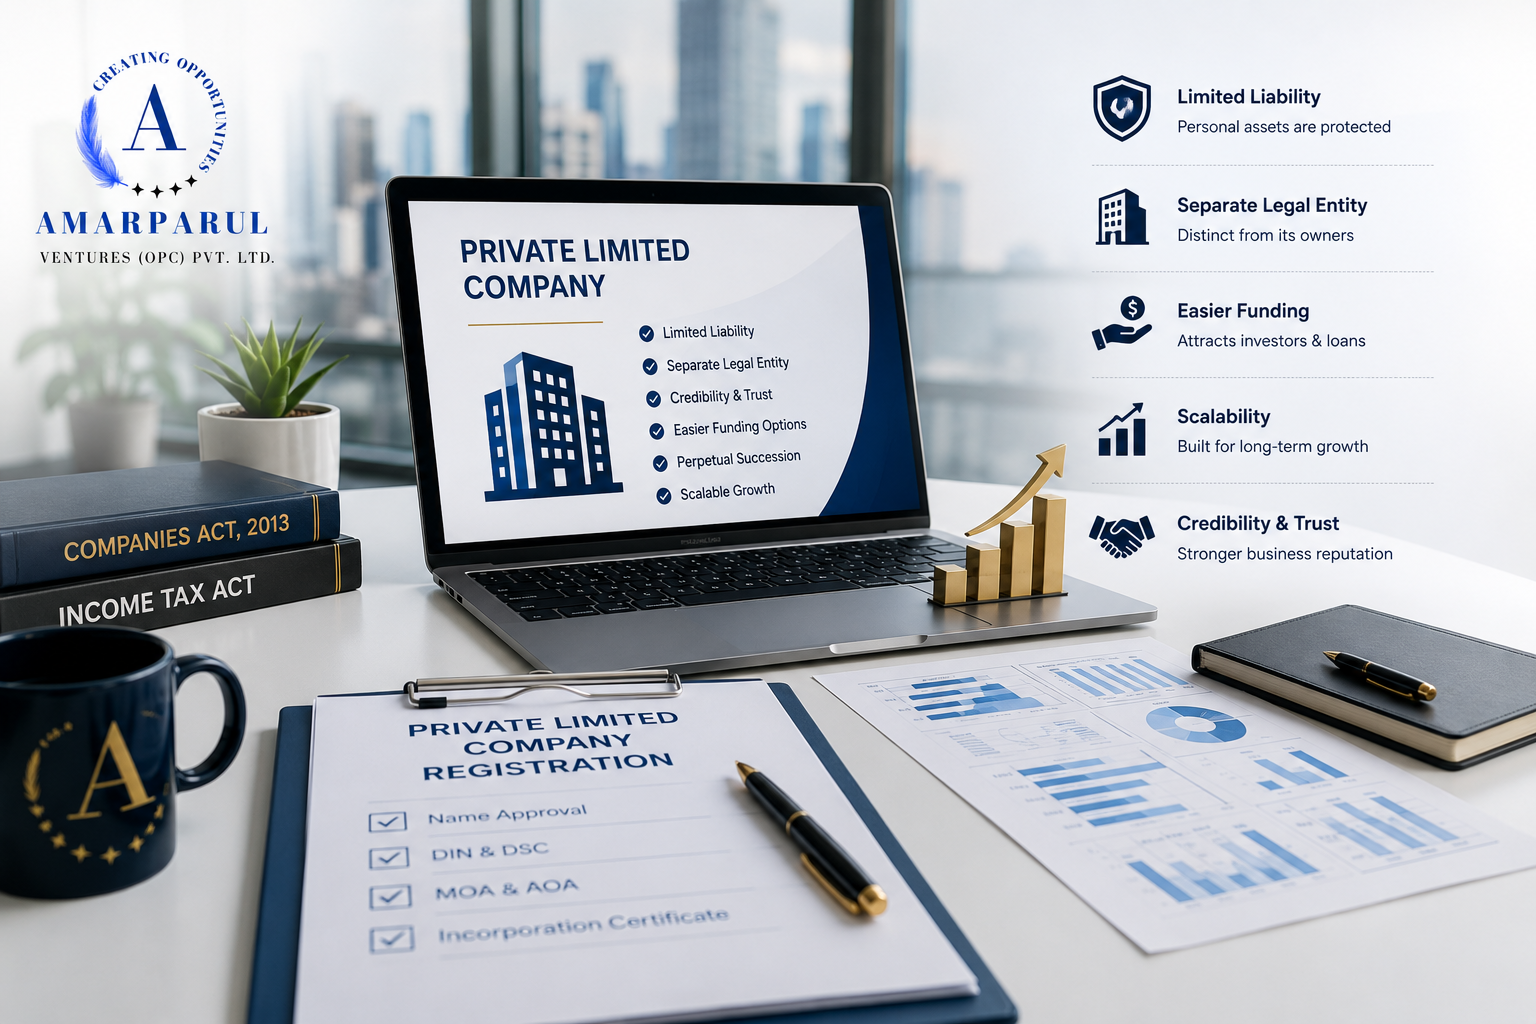
Why Most Startups Prefer Private Limited Companies
Limited Liability Protection for Founders
One of the biggest advantages of a Private Limited Company is limited liability.
In simple terms, the personal assets of founders usually remain protected if the company faces debts or financial losses. The liability of shareholders is generally limited to their shareholding in the company.
This becomes extremely important for startups because every new business involves some level of financial risk.
For example, if a startup takes business loans, signs vendor agreements, or enters large client contracts, the founders gain an additional layer of legal protection through the company structure.
This gives entrepreneurs more confidence to take calculated business risks while protecting personal financial stability.
Easier Fundraising Opportunities
Fundraising is one of the strongest reasons why startups prefer Private Limited Companies.
Most angel investors, venture capital firms, and institutional investors prefer investing in Private Limited Companies because the structure supports:
- equity distribution,
- shareholding clarity,
- investor rights,
- and ownership transfer.
Investors generally look for transparency and scalability before investing money into a startup. A Private Limited Company provides a more structured framework for investment compared to sole proprietorships or traditional partnerships.
This structure also allows startups to issue shares to investors in exchange for funding, which becomes essential during seed funding or growth-stage investment rounds.
As startups begin planning financial growth, working capital, or investor readiness, many founders also explore Finance Advisory Service for financial planning and business expansion support.
Better Credibility and Professional Trust
A registered Private Limited Company often creates a stronger impression among clients, vendors, investors, and enterprise partners.
When startups approach larger businesses for partnerships or contracts, having a Private Limited structure usually adds credibility.
Clients often feel more comfortable working with registered entities because:
- legal documentation is structured,
- ownership is transparent,
- and compliance obligations are more formalized.
This becomes particularly useful for startups entering:
- SaaS,
- fintech,
- consulting,
- IT services,
- e-commerce,
- or B2B industries.
A strong corporate structure can also support future business financing and growth opportunities through professional financial management and Corporate Finance Solutions.
ESOP Benefits for Startup Hiring
Hiring talented employees is one of the biggest challenges for startups.
Many growing startups use ESOPs (Employee Stock Ownership Plans) to attract and retain skilled professionals. ESOPs give employees ownership interest in the company through shares.
Private Limited Companies support ESOP structures much more efficiently than many other business structures.
This helps startups:
- attract better talent,
- improve employee retention,
- and build long-term team commitment.
For fast-growing startups, ESOP flexibility becomes an important growth advantage.
Easy Ownership Transfer and Scalability
As startups grow, ownership structures often evolve.
New co-founders may join, investors may enter, or shares may need to be transferred during funding rounds. A Private Limited Company makes these transitions comparatively easier.
The structure supports:
- share transfers,
- equity dilution,
- ownership restructuring,
- and future expansion.
This flexibility becomes important when startups scale operations across cities, onboard strategic partners, or prepare for mergers and acquisitions.
Separate Legal Identity
A Private Limited Company has its own legal identity separate from its founders.
This means:
- the company can own assets,
- enter contracts,
- open bank accounts,
- and continue operating even if ownership changes.
This structure creates long-term business continuity and improves operational clarity.
For startups planning sustainable growth, this becomes a major advantage.
Why Investors Prefer Private Limited Companies
Most investors prefer Private Limited Companies because the structure offers greater transparency, legal clarity, and investment flexibility.
Investors usually look for:
- defined shareholding patterns,
- formal governance,
- compliance structure,
- and clear ownership rights.
Private Limited Companies make it easier to:
- issue shares,
- onboard investors,
- create shareholder agreements,
- and manage equity dilution.
On the other hand, LLPs and sole proprietorships may create limitations during large-scale fundraising.
Many venture capital firms specifically prefer investing in Private Limited entities because the framework aligns better with startup funding ecosystems.
This is one reason why many startups convert into Private Limited Companies before raising external funding.
Private Limited Company vs LLP for Startups
Both LLPs and Private Limited Companies are popular business structures in India. However, the right choice depends on the startup’s long-term goals.
| Factor | Private Limited Company | LLP |
| Investor Preference | High | Limited |
| Equity Funding | Easy | Difficult |
| ESOP Support | Available | Limited |
| Compliance | Moderate | Lower |
| Scalability | High | Moderate |
| Ownership Transfer | Easier | More restricted |
| Startup India Recognition | Common | Available in some cases |
| Venture Capital Compatibility | Strong | Weak |
An LLP may work well for:
- small professional firms,
- freelancers,
- or businesses without aggressive scaling plans.
However, startups planning:
- fundraising,
- rapid expansion,
- ESOP implementation,
- or investor onboarding,
usually prefer Private Limited Companies.
Startup India Benefits for Private Limited Companies
Many startups also choose Private Limited Companies because the structure aligns well with Startup India recognition requirements.
Eligible startups may receive benefits like:
- tax exemptions,
- easier compliance support,
- government scheme access,
- and startup ecosystem recognition.
The exact eligibility depends on multiple conditions, including:
- company age,
- innovation focus,
- and turnover limits.
Tax planning becomes an important area for growing startups, especially during expansion and funding stages. Businesses often seek support from Taxation & Investment Advisory to manage startup taxation and financial structuring effectively.
Compliance Requirements You Should Know
While Private Limited Companies offer many advantages, founders should also understand the compliance responsibilities involved.
Some important compliance requirements include:
- ROC filings,
- annual returns,
- bookkeeping,
- accounting maintenance,
- GST compliance,
- statutory audits,
- and board-related documentation.
Many startups ignore compliance during the early stages and later face penalties or operational issues.
That is why maintaining proper accounting and legal documentation becomes extremely important from the beginning.
Startups looking for ongoing compliance management often use Accounting & Compliance Services to handle regulatory responsibilities more efficiently.
When a Private Limited Company May Not Be the Right Choice
Although Private Limited Companies are highly beneficial for startups, they may not be ideal for every business situation.
For example:
- freelancers,
- solo consultants,
- very small local businesses,
- or side-income ventures,
may not immediately require a Private Limited structure.
Since compliance and maintenance requirements are comparatively higher, founders should evaluate:
- business goals,
- funding plans,
- growth expectations,
- and operational scale before deciding.
Choosing the right structure depends on the long-term vision of the business.
Real Startup Example
Imagine two founders launching a SaaS startup in India.
Initially, they start with a small team and a limited budget. Within one year, they begin attracting enterprise clients and investor interest.
Now they need:
- funding,
- ESOP planning,
- structured ownership,
- and scalable compliance systems.
If the business was operating as a sole proprietorship or basic partnership, restructuring later could become complicated.
Because they started as a Private Limited Company, onboarding investors and scaling operations became smoother.
This is one of the biggest reasons why many startups prefer building the right legal foundation early.
Common Mistakes Startups Make While Choosing Business Structure
Choosing Structure Only Based on Low Compliance
Many startups select LLPs purely because compliance seems easier initially. But future fundraising requirements often create limitations later.
Ignoring Long-Term Scalability
Founders sometimes choose a structure suitable for today’s operations without considering future expansion plans.
Poor Shareholding Planning
Improper ownership planning during incorporation can create conflicts during funding rounds or co-founder restructuring.
Delaying Compliance Management
Ignoring filings, accounting, or documentation can create legal and financial problems later.
Businesses preparing for funding or expansion often benefit from proper documentation and Project Report Services for structured financial planning and investor presentations.
Final Thoughts
Choosing the right business structure is one of the most important decisions for any startup.
A Private Limited Company offers several advantages for businesses planning:
- long-term growth,
- fundraising,
- investor onboarding,
- scalability,
- and stronger market credibility.
At the same time, founders should also understand the compliance responsibilities involved and evaluate whether the structure aligns with their business goals.
For startups aiming to build a scalable and investment-ready business, Private Limited Companies often provide the flexibility and legal foundation needed for sustainable growth.
Businesses looking for startup registration guidance, compliance assistance, or professional advisory support can explore Amarparul Ventures for professional business and financial consulting services.
Frequently Asked Questions
Q1. Is a Private Limited Company best for startups?
For startups planning long-term growth, fundraising, and scalability, a Private Limited Company is often considered one of the best business structures in India.
Q2. Why do investors prefer Private Limited Companies?
Investors prefer Private Limited Companies because they support equity investment, structured ownership, shareholder agreements, and easier investment management.
Q3. Which is better for startups: LLP or Private Limited Company?
An LLP may work well for small businesses with limited scaling plans. However, startups planning funding and expansion usually prefer Private Limited Companies.
Q4. Can startups raise funding with LLP?
Yes, but raising investment through LLPs can become more complicated compared to Private Limited Companies.
Q5. What are the disadvantages of a Private Limited Company?
Some disadvantages include:
- higher compliance requirements,
- annual filings,
- audit obligations,
- and regulatory documentation.
Q6. Is Startup India registration possible for Private Limited Companies?
Yes, many startups registered as Private Limited Companies apply for Startup India recognition if they meet eligibility conditions.
Q7. How much does Private Limited Company registration cost in India?
The cost depends on factors like professional fees, documentation, government charges, and business requirements.
Q8. Can one person start a Private Limited Company?
India also offers One Person Company (OPC) registration for solo founders, depending on business requirements and eligibility.
The post Why Startups Prefer Private Limited Companies in India first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>The post PONZI Schemes : Beware first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>Every few years a new one hits the market. Initial investors make money and the latter ones lose money.
Of late a international entity has been in the news and is being investigated by various regulatory agencies of the government, including the ministry of corporate affairs. Several investor protection groups have alleged that the company is nothing but another Ponzi scheme.
What is Ponzi Scheme ?
Charles Ponzi, an Italian immigrant to the United States of America, promised this to investors way back in 1919. Born in Parma, Italy, in 1882, Ponzi, landed in the US in 1903.
In August 1919, in the process of issuing an export magazine, Ponzi realised that a huge arbitrage opportunity existed. Ponzi made an offer to a person in Spain requesting him to subscribe to an export magazine he planned to launch.
The subscriber sent Ponzi an international postal reply coupon, which could be exchanged at the local post office, for American stamps, needed to dispatch the magazine to Spain.
The coupon in Spain cost the equivalent of one cent in American currency. In America when Ponzi exchanged the coupon, he got six cents worth of stamps. Sensing the arbitrage opportunity, Ponzi decided to float an investment scheme.
Ponzi promised investors that he could double their money in 90 days. Money started pouring in as no other investments in the market at that point in time offered such high returns.
Once the money had been collected, Ponzi planned to convert American dollars into foreign currency, buy international postal reply coupons from various countries, convert them into American stamps and sell them for a huge profit.
The idea was brilliant. But Ponzi had not taken into account the difficulties involved in dealing with various postal organisations around the world, along with other problems involved in transferring and converting currency. Nevertheless, the investors got attracted to the huge returns the scheme promised.
At its peak, the scheme had 40,000 investors who had invested around $15 million in the scheme. Meanwhile, Ponzi had started living an extravagant life blowing up the money investors brought in.
On July 26, 1920, the Boston Post ran a story questioning the legitimacy of the scheme. Within a few hours, angry depositors lined up at Ponzi’s door, demanding their money back.
Ponzi asked his staff to settle their obligations. The anger subsided, but not for long. On August 10, 1920, the scheme collapsed. The auditors, the newspapers and the banks declared that Ponzi was definitely bankrupt.
It was revealed that only two stamps had been actually purchased. Money brought in by the new investors was used to pay off old investors.
The post PONZI Schemes : Beware first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>The post Liquidity Measurement Ratios first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>Types of Ratios
| Liquidity Measurement | Profitability Indicators | Financial Leverage/Gearing | Operating Performance | Investment Valuation |
| Current Ratio | Profit Margin Analysis | Equity Ratio | Fixed Assets Turnover | Price/Earnings Ratio |
| Quick Ratio | Return on Assets | Debt Ratio | Sales/ Revenue | Price/Earnings to Growth ratio |
| Return on Equity | Debt-Equity Ratio | Average Collection Period | Dividend Yield | |
| Return on Capital Employed | Capitalization Ratio | Inventory Turnover | Dividend Payout Ratio | |
| Interest Coverage Ratio | Total assets Turnover |
Liquidity Measurement Ratios
Liquidity refers to the ability of a firm to meet its short-term financial obligations when and as they fall due. The main concern of liquidity ratio is to measure the ability of the firms to meet their short-term maturing obligations. The greater the coverage of liquid assets to short-term liabilities the better as it is a clear signal that a company can pay its debts that are coming due in the near future and still fund its ongoing operations. On the other hand, a company with a low coverage rate should raise a red flag for investors as it may be a sign that the company will have difficulty meeting running its operations, as well as meeting its obligations.
| Ratio | Formula | Meaning | Analysis |
| Current Ratio | Current Assets/Current Liabilities Current assets includes cash, marketable securities, accounts receivable and inventories. Current liabilities includes accounts payable, short term notes payable, short-term loans, current maturities of long term debt, accrued income taxes and other accrued expenses | The number of times that the short term assets can cover the short term debts. In other words, it indicates an ability to meet the short term obligations as & when they fall due | Higher the ratio, the better it is, however but too high ratio reflects an in-efficient use of resources & too low ratio leads to insolvency. The ideal ratio is considered to be 2:1., |
| Quick Ratio or Acid Test Ratio | (Cash+CashEquivalents+Short Term Investments+Accounts Receivables) / Current Liabilities | Indicates the ability to meet short term payments using the most liquid assets. This ratio is more conservative than the current ratio because it excludes inventory and other current assets, which are more difficult to turn into cash | The ideal ratio is 1:1. Another beneficial use is to compare the quick ratio with the current ratio. If the current ratio is significantly higher, it is a clear indication that the company’s current assets are dependent on inventory. |
Profitability Indicators Ratios
Profitability is the ability of a business to earn profit over a period of time.The profitability ratios show the combined effects of liquidity, asset management (activity) and debt management (gearing) on operating results. The overall measure of success of a business is the profitability which results from the effective use of its resources.
| Ratio | Formula | Meaning | Analysis |
| Gross Profit Margin | (Gross Profit/Net Sales)*100 | A company’s cost of goods sold represents the expense related to labor, raw materials and manufacturing overhead involved in its production process. This expense is deducted from the company’s net sales/revenue, which results in a company’s gross profit. The gross profit margin is used to analyze how efficiently a company is using its raw materials, labor and manufacturing-related fixed assets to generate profits. | Higher the ratio, the higher is the profit earned on sales |
| Operating Profit Margin | (Operating Profit/Net Sales)*100 | By subtracting selling, general and administrative expenses from a company’s gross profit number, we get operating income. Management has much more control over operating expenses than its cost of sales outlays. It Measures the relative impact of operating expenses | Lower the ratio, lower the expense related to the sales |
| Net Profit Margin | (Net Profit/Net Sales)*100 | This ratio measures the ultimate profitability | Higher the ratio, the more profitable are the sales. |
| Return on Assets | Net Income / Average Total Assets ( Earnings Before Interest & Tax = Net Income) | This ratio illustrates how well management is employing the company’s total assets to make a profit. | Higher the return, the more efficient management is in utilizing its asset base |
| Return on Equity | Net Income / Average Shareholders Equity*100 | It measures how much the shareholders earned for their investment in the company | Higher percentage indicates the management is in utilizing its equity base and the better return is to investors. |
| Return on Capital Employed | Net Income / Capital Employed Capital Employed = Avg. Debt Liabilities + Avg. Shareholders Equity | This ratio complements the return on equity ratio by adding a company’s debt liabilities, or funded debt, to equity to reflect a company’s total “capital employed”. This measure narrows the focus to gain a better understanding of a company’s ability to generate returns from its available capital base. | It is a more comprehensive profitability indicator because it gauges management’s ability to generate earnings from a company’s total pool of capital. |
Financial Leverage/Gearing Ratios
These ratios indicate the degree to which the activities of a firm are supported by creditors’ funds as opposed to owners as the relationship of owner’s equity to borrowed funds is an important indicator of financial strength. The debt requires fixed interest payments and repayment of the loan and legal action can be taken if any amounts due are not paid at the appointed time. A relatively high proportion of funds contributed by the owners indicates a cushion (surplus) which shields creditors against possible losses from default in payment.
Financial leverage will be to the advantage of the ordinary shareholders as long as the rate of earnings on capital employed is greater than the rate payable on borrowed funds.
| Ratio | Formula | Meaning | Analysis |
| Equity Ratio | (Ordinary Shareholder’s Interest / Total assets)*100 | This ratio measures the strength of the financial structure of the company | A high equity ratio reflects a strong financial structure of the company. A relatively low equity ratio reflects a more speculative situation because of the effect of high leverage and the greater possibility of financial difficulty arising from excessive debt burden. |
| Debt Ratio | Total Debt / Total Assets | This compares a company’s total debt to its total assets, which is used to gain a general idea as to the amount of leverage being used by a company. This is the measure of financial strength that reflects the proportion of capital which has been funded by debt, including preference shares. | With higher debt ratio (low equity ratio), a very small cushion has developed thus not giving creditors the security they require. The company would therefore find it relatively difficult to raise additional financial support from external sources if it wished to take that route. The higher the debt ratio the more difficult it becomes for the firm to raise debt. |
| Debt – Equity Ratio | Total Liabilities / Total Equity | . This ratio measures how much suppliers, lenders, creditors and obligors have committed to the company versus what the shareholders have committed. This ratio indicates the extent to which debt is covered by shareholders’ funds. | A lower ratio is always safer, however too low ratio reflects an in-efficient use of equity. Too high ratio reflects either there is a debt to a great extent or the equity base is too small |
| Capitalization Ratio | Long Term Debt / (Long Term Debt + Shareholder’s Equity) | This ratio measures the debt component of a company’s capital structure, or capitalization (i.e., the sum of long-term debt liabilities and shareholders’ equity) to support a company’s operations and growth. | A low level of debt and a healthy proportion of equity in a company’s capital structure is an indication of financial fitness. A company too highly leveraged (too much debt) may find its freedom of action restricted by its creditors and/or have its profitability hurt by high interest costs. This ratio is one of the more meaningful debt ratios because it focuses on the relationship of debt liabilities as a component of a company’s total capital base, which is the capital raised by shareholders and lenders. |
| Interest Coverage Ratio | EBIT / Interest on Long Term Debt | This ratio measures the number of times a company can meet its interest expense | The lower the ratio, the more the company is burdened by debt expense. When a company’s interest coverage ratio is only 1.5 or lower, its ability to meet interest expenses may be questionable. |
Operating Performance Ratios:
These ratios look at how well a company turns its assets into revenue as well as how efficiently a company converts its sales into cash, i.e how efficiently & effectively a company is using its resources to generate sales and increase shareholder value. The better these ratios, the better it is for shareholders.
| Ratios | Formula | Meaning | Analysis |
| Fixed Assets Turnover | Sales / Net Fixed Assets | This ratio is a rough measure of the productivity of a company’s fixed assets with respect to generating sales | High fixed assets turnovers are preferred since they indicate a better efficiency in fixed assets utilization. |
| Average Collection Period | ( Accounts Receivable/Annual Credit Sales )*365 days | The average collection period measures the quality of debtors since it indicates the speed of their collection. | The shorter the average collection period, the better the quality of debtors, as a short collection period implies the prompt payment by debtors. An excessively long collection period implies a very liberal and inefficient credit and collection performance. The delay in collection of cash impairs the firm’s liquidity. On the other hand, too low a collection period is not necessarily favorable, rather it may indicate a very restrictive credit and collection policy which may curtail sales and hence adversely affect profit. |
| Inventory Turnover | Sales / Average Inventory | It measures the stock in relation to turnover in order to determine how often the stock turns over in the business. It indicates the efficiency of the firm in selling its product. | High ratio indicates that there is a little chance of the firm holding damaged or obsolete stock. |
| Total Assets Turnover | Sales / Total Assets | This ratio indicates the efficiency with which the firm uses all its assets to generate sales. | Higher the firm’s total asset turnover, the more efficiently its assets have been utilised. |
Investment Valuation Ratios:
These ratios can be used by investors to estimate the attractiveness of a potential or existing investment and get an idea of its valuation.
| Ratio | Formula | Meaning | Analysis |
| Price Earning Ratio ( P/E Ratio ) | Market Price per Share / Earnings Per Share | This ratio measures how many times a stock is trading (its price) per each rupee of EPS | A stock with high P/E ratio suggests that investors are expecting higher earnings growth in the future compared to the overall market, as investors are paying more for today’s earnings in anticipation of future earnings growth. Hence, stocks with this characteristic are considered to be growth stocks. Conversely, a stock with a low P/E ratio suggests that investors have more modest expectations for its future growth compared to the market as a whole. |
| Price Earnings to Growth Ratio | ( P/E Ratio ) / Earnings Per Share | The price/earnings to growth ratio, commonly referred to as the PEG ratio, is obviously closely related to the P/E ratio. The PEG ratio is a refinement of the P/E ratio and factors in a stock’s estimated earnings growth into its current valuation. By comparing a stock’s P/E ratio with its projected, or estimated, earnings per share (EPS) growth, investors are given insight into the degree of overpricing or under pricing of a stock’s current valuation, as indicated by the traditional P/E ratio. | The general consensus is that if the PEG ratio indicates a value of 1, this means that the market is correctly valuing (the current P/E ratio) a stock in accordance with the stock’s current estimated earnings per share growth. If the PEG ratio is less than 1, this means that EPS growth is potentially able to surpass the market’s current valuation. In other words, the stock’s price is being undervalued. On the other hand, stocks with high PEG ratios can indicate just the opposite – that the stock is currently overvalued. |
| Dividend Yield Ratio | ( Annual Dividend per Share / Market Price per Share ) *100 | This ratio allows investors to compare the latest dividend they received with the current market value of the share as an indictor of the return they are earning on their shares | This enables an investor to compare ratios for different companies and industries. Higher the ratio, the higher is the return to the investor |
| Dividend Payout Ratio | (Dividend per Share / Earnings per Share ) * 100 | This ratio identifies the percentage of earnings (net income) per common share allocated to paying cash dividends to shareholders. The dividend payout ratio is an indicator of how well earnings support the dividend payment. |
- turquoises.org
- tinytownnj.com
- sumibol.com
- styogawear.com
- sofrologiaonline.com
- kpukabngawi.online
- sanandaya-prod.org
- promosuzukiignis.com
- pickbestheadsets.com
- paroisse-de-tarascon.com
- oleoleindonesia.com
- mydigitalevo.com
- mejorescafeteras.com
- lythbound.com
- lequilibreduchien.com
- kusonganamocambique.org
- jamonua.com
- getindx.com
- fimcoestate.com
- cndustfilterbag.com
- bios-shield.com
- ambitiouswomenconference.com
- czgunsusastore.com
- nickmarzullomusic.com
- popconverter.com
- janalees.com
- daniello-store.com
- anninhvps.com
- hashtaggadgetz.com
- imageuploading.net
- edureaders.com
- production-matsumoto.com
- palabranueva.org
- jardindetasoeur.org
- journalspotting.com
- acharipickle.com
- mezu-coffee.com
- ionianenvironmentfoundation.org
- techoscience.com
- gushireview.com
- ithinkspanish.com
- writeideas101.com
- artfullposters.com
- barnstable-democrats.com
- maggiemakesitbetter.com
- cyclowing.com
- actual-synergy.com
- lyrikshub.com
- wildwordsfest.com
- fabufluff.com
- nimportnawak.com
- angelisimashop.com
- oriandme.com
- fluerly.com
- sphmnetwork.com
- acte3editions.com
- jaguarresources.com
- geardurr.com
- alsudaisoud.com
- mimarestore.com
- onetisa.com
- ka2kadeh2.com
- aldercarcarehome.com
- mcsstreaming.com
- jcceewatkinsbarney.com
- bilkem.org
- greatlakeslore.com
- infinitelyadaydreamer.com
- moonshine-master.com
- findomwebcams.com
- minecraftserversreview.com
- floridaelitesw.com
- babyluxify.com
- vpatees.com
- sylasshirt.com
- sgvapesghub.com
- learnpaidmedia.com
- theaveragedriver.com
- vikingvise.com
- nansuniqueshop4men.com
- parksideofglenview.com
- congdol.com
- washburnillinois.org
- ryptgym.com
- eliteshopexpress.com
- oliveandbeanboutique.com
- latestpinay.com
- csbakeware.com
- rightbrainedmom.com
- comfortpaintingandremodelingnv.com
- cinematiccaptures.com
- phantommobil.com
- bluemonkeyperformance.com
- ayintaphaber.com
- dreamspaze.com
- hovalot-express.com
- shortlinereview.com
- apparentlyexempt.com
- topazpharma.com
- smartwatchgraph.com
- arrowgamingglasses.com
- marltonbistro.com
- sunumvaaz.com
- printersbin.com
- yvonnegpearson.com
- dragonpicture.net
- miomana.com
- otto-vintage.com
- pacificbling.com
- ermannopitacco.com
- alyamamah-auto.com
- megahaber35.com
- flaminglife.com
- harmonyfarmcandles.com
- patchandcoframes.com
- demarques-et-vous.com
- mybigcamera.net
- foreverbeautycollection.com
- alvaapparel.com
- meghacabs.com
- andonpokayoke.com
- lasnuevastecnologias.com
- MapsLoans.org
- salon-adb.com
- thudhu.com
- series-ss.com
- chigrp.com
- waytoadmissions.com
- stardewitemsids.com
- buddyscustombaits.com
- montajat.net
- natureera.net
- vortexcustomerservice.com
- prohindistatus.com
- spiritualrats.com
- viewgame.net
- upfreshfranchise.com
- randolacaminade.com
- crazy-irrumatio.net
- growing-years.net
- corinneb-arthurimmo.com
- pro-du-code.com
- ajfuryfight.com
- marchempls.com
- toyotabornforthis.com
- nurmuizaspils.com
- latestserialgossip.com
- venesemmorganlaw.com
- juegoskb.com
- babloonstudios.com
- camp-club.net
- collectionheavyduty.com
- lynnmikolajczak.com
- bidouyoga.com
- lifetreeayurveda.com
- graftoutdoors.com
- cars-sell.net
- wartapedia.net
- yarmouktvsat.com
- hidalgoelectrodomesticos.com
- edificiodelicias.com
- dikurat-alsharqia.com
- re-sha.com
- turisindo.com
- callgirlskolkata.net
- top-touch.net
- bloombydesignco.com
- coc-layouts-wiki.com
- sio-nayuta.com
- real-financial-dynamics.com
- moroccotravelway.com
- binmarta.com
- kipinenergy.com
- leovdboogaard.com
- tellmeacharm.com
- hindimesuchna.com
- covabase.com
- savvypalette.com
- auditsocial.org
- bluelagoonlodgehuahine.com
- physickle.com
- outdoorfurnitureindonesia.com
- vereasnegras.com
- yarininegitimizirvesi.com
- hiddenworldgin.com
- kyoto-carappo.net
- cellphonei.com
- mikeforfrederick.com
- hoursinformer.com
- a2theme.com
- miniontees.com
- socialspeaker.net
- katsuragi-hanabi.com
- peanutmutterrescue.org
- bjjinspired.com
- mexampac.org
- idunn-watches.com
- chezanimaux.com
- salvetx.com
- terapiabrevecentradaensoluciones.com
- whenwhereco.com
- wcdoit.com
- kampouridespoina.com
- centrocommerciale-airone.com
- frutasdeeuropa.com
- clearchoiceres.com
- gabinete-psicologico.net
- rugwix.net
- bagmagstore.com
- esoespoliticamenteincorrecto.com
- middlemanagement-tamao.com
- centrocommerciale-brescia.com
- sheilalovesbooks.com
- bibanko6.com
- joguno.com
- allsimbaseball9.com
- youmovise.com
- intojerseys.com
- sathajada-sa.com
- soremoiiyan.com
- county-house.com
- thephotographyfund.com
- nutrialhealth.com
- shenkmachinery.com
- fatburnromania.com
- demonslayeroutlet.com
- xylonwatch.com
- dashimaki-schranz.com
- eazsocialmedia.com
- jessicaleesocial.com
- moscowrentestate.com
- petuko.com
- arteprensa.com
- iklimbekoservisi.com
- iseweurope.com
- mejorestensiometros.com
- drjaqlyn.com
- lpcamozzi.com
- heregoeskate.com
- ortheband.com
- demigarciasabat.com
- flavorcityoils.com
- fabryka-studio.com
- realbarrier-jp.com
- arqueologiadacriacao.org
- tusfinanzasfaciles.com
- maroc-recettes.com
- pinchednerveclinic.com
- sunisout.org
- axelbarrel.com
- danieleangelomartino.org
- todai-mono-lab-japan.com
- m-albaghli.org
- minimodernpaintings.com
- centrocommerciale-lentate.com
- sapphireinvestmentgroup.com
- emsaocarlos.com
- merleandpaz.com
- poweretty.com
- haryanajobportal.com
- cracksofts.net
- tentopdatingsites.com
- movestyles.com
- motostorelocator.com
- bloomingdaleschool.org
- dlja-windows.com
- littletravelprincess.com
- shiningnames.com
- trollslandatoystore.com
- tarrahan-co.com
- mcbaronfootball.com
- organic-suirens.com
- coquitlamcohousing.com
- mothercare-coupon.com
- pestcontrol-alryad.com
- jaredtalavera.com
- fizjorytm.com
- mumzworld-coupon.com
- vitadapappagalli.org
- hnihpainetwork.com
- aziz-anzabi.com
- storewestern.com
- techteacherslog.net
- awaysheetmusic.com
- sergeylutsenkoart.com
- acpel.org
- elazigsatrancakademi.com
- redoxldn.com
- thegang-online.com
- thebigsismovement.com
- medyumdolunay.net
- cachitasnow.com
- voilacreations.com
- copehu.org
- clover-gunma.com
- underseawear.com
- medifooteilat.com
- storozhinets-forest.com
- olaymerkezi.com
- laceyleyla.com
- spsc20knotsnob.com
- horas-espejo.com
- worldlifeadvice.com
- masteringnetworks.com
- gardengild.com
- svwebgrrls.com
- promoddy.com
- citations-ses.net
- shopfreshpasta.com
- aaman-sa.com
- thebestfootballs.com
- cancerprotalk.com
- mayfieldcellphonerepairs.com
- textilesblankas.com
- xcitenow.com
- makanarea.com
- smartmum.org
- jgowdyconsulting.com
- oregontravelingtours.com
- ekimena.com
- thecrayonbug.com
- clouddesktopservice.com
- bitlink-defi.com
- systemgoodcondition.com
- littledittle.com
- tawara-an.com
- windowinstallationmidlandtx.com
- nano-loo.com
- poleaholic.com
- baco-music.com
- toepferlaedchen.com
- radioencuentros.com
- southeastbeautifulkratom.com
- janimakinen.com
- beautyclou.com
- catchycustom.com
- worldwithfalak.com
- deepwellsubmersible.com
- cultishsupply.com
- omegarquitectas.com
- deathlogbook.com
- polymate3d.com
- brucecroskeyrealestate.com
- aui-techno.com
- ozyavuztesisat.com
- festival-cipke.com
- publikasiilmiah.com
- nepaletvous.org
- betasetup.com
- littlethatchflorist.com
- thegovtupdates.com
- thecitadelpub.com
- fisioterapiaalmeria.net
- urdupoetryworld.com
- arbolcomputer.com
- itaprotect.com
- gildong.net
- skimmerspaninigrill.com
- alfananine.com
- modelbouwmati.com
- surgileonline.com
- advancingbioelectronicmedicine.org
- blacklinenews.com
- enterpriseapts.com
- timedistancecalculation.com
- thehaggardhalo.com
- hijosdelsigloxxi.com
- ankaraepoksizemin.net
- clubdeescrituracyrano.com
- benimtesbihim.com
- armstronglawrva.com
- burundukino.net
- marketingmobilsuzuki.com
- ipl-tretmani.com
- dukan-t.com
- gaengkunbl.com
- generalhealthfitness.com
- liesvelvetpolet.com
- mumuonlineshops.com
- glue-note.com
- fukuokakaigi.com
- latelierduloup.com
- yksikhunt.com
- adambarbergroup.com
- ventodokite.com
- educatorhotspot.com
- essaytome.com
- volleyballsinfo.com
- and-camicie.com
- diegodallapalmaoutlet.com
- zvukon.net
- careswayhealth.com
- rd7comunica.com
- httptplinkrepeater.com
- lesdouceursdesbauges.com
- vsekreditnyekarty.com
- astream345.com
- clinikind.com
- audacedesignstudio.com
- urbanflag.org
- ebusinesstalks.com
- kepalabergetarz.net
- bornamelanews24.com
- daiichi-tantei-tochigi.com
- daiichi-tantei-gunma.com
- retetedemamica.com
- petvetfoodtips.com
- poomasafire.com
- stussyhoodies.net
- eileenbell.com
- studyabroadaids.net
- stormfc.net
- betflixpr.com
- graham-grahamlaw.com
- nirakle.com
- timdaily-buy2sell.com
- e-toro-forex.com
- cheapbookingflight.com
- jamalek3almy.net
- mobesekameracanliizle.com
- powertoolspro.net
- eatsumgreens.com
- puppyconnect.org
- keepjudgechrisbrook.com
- ixiartgallery.com
- bagsbrothers.com
- sustaindatacenter.com
- collectiongolfgti.com
- pouceencm.net
- spherequotes.com
- skinhauss.com
- testakw.com
- sia-architecture.com
- onshoesfactoryoutletstore.com
- lojaalohaexpress.com
- ibeldisouk.com
- monellisi.com
- velvetcartstore.com
- ro-zero.com
- sylvieperaud.com
- zaykastar.com
- menardsnz.com
- servimudanzasecuador.com
- earth-v.com
- diendangame.net
- islamioda.net
- kanyewestmerchllc.com
- mobilehomeprotalk.com
- carhartthoodie.net
- farmprotalk.com
- monocolar.com
- ksvhelmstedt.com
- maboxensorcelee.com
- popninja.net
- machinistsfriend.com
- amalalfoam.com
- timearamesh.com
- sekizdizayn.com
- retunesthe.com
- tiendakrona.com
- riha-axis.com
- brownfieldsports.net
- childmall-egy.com
- blossomingpress.com
- windowtintingtoday.com
- darkriser.com
- kabmart.com
- terarose.com
- wrapallaboutitanddyehappy.com
- trendvonal.com
- positivityloop.com
- thelgservicecenter.com
- vipistanbulturizm.com
- motormaniax.com
- dailyjonomot.com
- 724bileklik.com
- white-parts.de
- xpertcheck.de
- tastatur-mit-touchpad.de
- st-michaelsbund-regensburg.de
- wmekip.com
- wingsnbags.com
- vulkanlux.com
- uman-map.com
- tonemasseve.com
- denledphuchai.com
- tilleul-festival.com
- thestarswesaw.com
- thehomewind.com
- thebougecruise.com
- thebeirutforum.com
- tellthebelllsurvey.org
- teecina.com
- taiacore.com
- springroove2021.com
- spheretactics.com
- smartfixghana.com
- rotwandeins.de
- ladygagachromaticaballmerch.de
- jaegerhof-essen.de
- shiawaseseisakujo.com
- sbanglanews.com
- rospages.org
- proxytoolsbox.com
- provitalcosmetics.com
- pixmaweb.com
- pinkninjakitty.com
- pennyscustomgifts.com
- nripja.com
- newlyricsmedia.com
- namiceofficial.com
- nairaolshop.net
- muzicsome.com
- momscounsel.com
- miso88vn.com
- materialsscienceforum.com
- magicmushroomstore.net
- lsprrun.com
- legado-shop.com
- komachimama.com
- klasspor.tv
- jpcaat.com
- jeong-good.com
- irobowifilogin.com
- investirglobal.com
- hindi2news.in
- frerichsundcordes.de
- hopoteez.com
- hmnews.net
- herbs4usa.com
- goguideonline.com
- georgiaphelpsbeautyblog.com
- ganave24.com
- funcity33mys.com
- funcity33myr.com
- eventswithphotobooth.com
- englishsun.org
- emeraldkalama.com
- egyptiandrugindex.com
- drmohamedelkaseer.com
- diosloscria.org
- divardecor.com
- dichvukekhaithue247.com
- dallasmavericksclub.com
- crossfitworkovertime.com
- course-experience.com
- compagnieduchaos.com
- cleverminu.com
- christianfaithstore.com
- chungkhoanviet.net
- celebrity-osaka.com
- caribefm.com
- burzi-obiavi.com
- buckfastleigh.org
- b-faast.com
- bebidasycopas.com
- ashleytuckerdesigns.com
- armoredtalk.com
- amalmp.com
- alphapsilocybins.com
- abtehnic.com
- aajtakgujarat.com
- gadgetsreviews.in
- tabrizmusic.net
- wahjalhafl.com
- theblaemblaem.com
- phamquocdat.net
- noticiasyprogramas.com
- saralchemical.com
- vanithasmakeover.com
- shrimaangroups.com
- maydiengiaichat.com
- bookbaopr.com
- jubileegastronomy.com
- 7migliori.net
- florinda-eg.com
- turtlespet.com
- ashtarmag.com
- todaygkallexams.com
- atasehircicekonline.com
- tipsyconsejos.com
- pabriksepatubogor.com
- lightreadingsmag.com
- baldwinhillsclassroom.org
- 3mdcrossfit.com
- olamio.com
- ashroyfoundation.org
- cobargocommunitytreeproject.org
- yugiyahirano.com
- golshidgroup.com
- puppieslisting.com
- galeriaandrychow.com
- regina4pueblo.com
- swindonlightningcheerleading.com
- hoyafederal.org
- valleyautofm.com
- olivessentials.com
- ebooks-land.net
- alinabears.com
- fredebami.com
- 3b-international.com
- needaccountinghomeworkhelp.com
- yourribbonstore.com
- redhombresigualdadgranada.org
- youthreferencehub.com
- nikhandymanwolverhampton.com
- tiendamizunocolombia.com
- ussclamagore.org
- nbfest.com
- gocoastalrowing.com
- judgechrisdillon.com
- tsutawaru-saiyo-animation.com
- sanatuser.com
- daimielenconcierto.com
- puertascorrederasde.com
- casaesferica.net
- hashtagmasr.net
- glameursappeal.com
- heriadrov.com
- facinfissi.com
- sanctuarydowntownseattle.com
- a-tom.net
- naynaeshop.com
- publikmusic.com
- wielerkledingsnl.com
- happydadseltzerstore.com
- marijuana4eu.com
- hyronline.com
- aficionadosalafotografia.com
- green-barn.com
- kitschisland.com
- parwanibuildcon.com
- asejustplay.com
- aapbhijaano.com
- creatiefmedia.com
- ohcrocs.com
- tarrynsimone.com
- kwotimation.com
- rental-sim.com
- kadenkagu.com
- leahmariaclothingandco.com
- formatosdeplantillas.com
- selfcareluxe.com
- toyota-padang.com
- extraversions.com
- residenciasmoncasol.com
- massage-domicile.com
- chaparrashop.com
- fixerscoffee.com
- zeinnas.com
- detal-ka.com
- rtwiseowls.com
- crumpetsteaandsewing.com
- elhadatheco.com
- hydrofitnessgym.com
- kilisyoreselurunler.com
- istanbulotogarrentacar.com
- ekastationery.com
- redrama.org
- thelocalgraincompany.com
- yuyi4you.com
- raluland.com
- triachichi.com
- fuegoatierra.com
- artimarzialiga.com
- thepetspace.net
- congresoeducacionunir.net
- tkpsdasultengprov.com
- amp-1tiara4d.xyz
- lebah4d-amp.com
- tiara4d-amp.com
- edwinslot-amp.com
- laris4d-amp.com
- lebah4d-alternatif.com
- laris4d-alternatif.com
- tiara4d-alternatif.com
- edwinslot-alternatif.com
- edwin-slot-gacor.shop
- edwin-slot-gacor.site
- edwin-slot-gacor.store
- tiara4d-alternatif.shop
- amp-tiara4d.shop
- amp-tiara4d.xyz
- laris4d-slot-gacor.online
- laris4d-slot-gacor.shop
- lebah4d-slot-gacor.online
- amp-lebah4d.shop
- amp-lebah4d.site
- tiara4d-xyz.shop
- corlaslot-xyz.site
- corlaslot-gacor.site
- corlaslot-amp.xyz
- champion4d-amp.xyz
- tiara4d-gacor.xyz
- pastigacordilebah.xyz
- scatterhitam-lebah4d.com
- lebah4d-slottoto.com
- lebah4dtogel.com
- lebahamp.com
- ampforlebah4d.com
- jagonyalebah.xyz
- selalumenangditiara4d.xyz
- lebah4dsitusslotterbaik.xyz
- lebah4d-slot4dterbaik.xyz
- lebah4dslot4d.com
- tiara4dgacor.com
- lebah4dgacornih.com
- lebahnihboss.xyz
- laris4damp.xyz
- slottiara4d.com
- tiaragacor.xyz
- tiaraslot4d.xyz
- edwinslot4d.xyz
- slottiara4donline.xyz
- lebahslotmaxwin.xyz
- lebah4donline.xyz
- lebahslot20k.com
- lebah4dslotviralhariini.xyz
- edwinslot-amp.xyz
- amp4dslotlebah.com
- prediksihklebah.xyz
- slotdana10k-amp.xyz
- slottiara4d.xyz
- ampforlebah4d.xyz
- depocuman10k.xyz
- tiara4d-slot.xyz
- slotserverasialebah.xyz
- slotthailandpro.xyz
- situsbanyakmenangtiara4d.com
- slotqristiara.com
- amplebah4d.xyz
- slotserverasia.xyz
- slotterpercayatiara4d.com
- slotdemopragmatic.xyz
- slotlebah4d.xyz
- slotsbobettiara4d.xyz
- ampmaxwinedwinslot.xyz
- bandartototiara.xyz
- maindisituslebah.com
- daftarsegeradilebah4d.com
- menangdikaya.xyz
- selalumaxwindilebah.com
- selalujpdikaya.xyz
The post Liquidity Measurement Ratios first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>The post Terms Used in an IPO first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>1. IPO : IPO stands for Initial Public Offer. An IPO is the first sale of shares of a company to the general public. The promoters of the company, after complying with the various guidelines of SEBI (Securities and Exchange Board of India) and The companies Act, ask the public at large to subscribe to their shares so that they can generate capital and utilize the same for expanding their business. A successful IPO can raise a substantially huge amount of capital.
2. FPO : FPO stands for Follow-on Public Offer. Once a company comes with an IPO , it gets listed on the stock exchanges. After a certain period of time, if the company again intends to raise capital from the general public, then it again comes with a public issue which is called an FPO (Follow-on Public Offer ). It is a supplementary issue made by a company once it is listed and established on the stock exchange. In short, the first public issue of a company is an IPO, and any further public issue of the same company is called an FPO. For example, Shipping Corporaton of India (SCI), a listed company, is again coming up with a public issue which will be its FPO ( i.e. a second public issue)
3. Listing : Once the issue gets subscribed and the shares are allotted, they are listed on a recognized stock exchange e.g. BSE, NSE etc. Listing means that company has adhered to the terms and conditions of the stock exchange and its shares are now a part of the list of shares which can be traded on the stock exchange. Post listing, any investor can sell the shares, allotted at the time of the issue, in the secondary market.
4. Bid-cum-Application Form : For applying in any public issue, each investor must fill a standard form providing all the relevant details like Name, PAN, Demat id, Bank account details, Bid price, Number of shares applied etc. Such a form is called a Bid-cum-Application form. It can be submitted through the offline or online mode. An investor must ensure that all the relevant details are filled correctly to avoid rejection of application and to ensure smooth allotment of securities.
5. Price Band : A price band is the range of price within which an investor can place his bid for the securities. The price mentioned by the investor in the bid-cum-application form can neither be less than the lower limit of the price band nor can it exceed the upper limit of the price band. For example, In the recent IPO of Coal India, the price band was Rs. 225-245 per share, which means that an investor can bid only within the range of Rs. 225 to Rs. 245
6. Floor Price : In a price band, the lowest price is called the floor price, below which a bid cannot be placed. In the above example Rs. 225 is the floor price of the Coal India IPO
7. Cap Price : Cap price is the upper ceiling limit in a price band beyond which a bid cannot be placed. Again, taking the same example of Coal India, Rs. 245 is the Cap price, beyond which you cannot place the bid.
8. Minimum order quantity : Minimum Order Quantity is the minimum number of shares which the investor has to apply for in a public issue. For example, in the case of Coal India’s IPO, the minimum order quantity was 25, i.e. an investor has to bid for atleast 25 shares.
9. Market Lot : If an investor wants to bid for shares which are more than the minimum order quantity, then he can do so by bidding in multiples of a certain number of shares which is known as the Market Lot. By continuing the above example, if an investor wants to apply for more than 25 shares of Coal India, then bids can be made in multiples of 25 shares, which is the market lot size in case of the Coal India issue. Thus, applications can be made for 25, 50, 75 …….number of shares until the maximum subscription limit is reached. In case of Coal India, the minimum order quantity and market lot size, both were 25 shares.
10. Maximum Subscription Limit for Retail Investors : Maximum Subscription Limit for Retail Investors is the maximum amount of investment which can be made though a single bid-cum-application form, or simply speaking, by a single individual, in a public issue. Previously, retail investors were allowed to make an application of a maximum of Rs. 1,00,000, but now SEBI has increased this limit to Rs. 2,00,000. Any application by an retail investor which exceeds Rs. 2,00,000 becomes an application by a High Net Worth Individual (HNI), thus disabling the investor to enjoy the benefits of discount which are offered in some big ticket IPOs to the retail investors.
11. Cut Off Price : In book building issues, the issuer company specifies a price band within which the bids are made. The actual issue price can be any price above the floor price and within the price band. This issue price is called the Cut Off Price. This price is determined after considering the demand for the stock by the investors. Investors, in order to get allotments in big ticket public issues, bid at the cut off price, conveying their intention that they are willing to pay any price for the stock within the price band, at the end of the book building process.
12. ASBA (Application Supported by Blocked Amounts) : ASBA is an alternative mode of making payments in public issues whereby the application money stays in the bank account of the investor until the allotment is made. Only that much amount of funds are debited to the investor’s bank account for which the allotment is made and the rest of the blocked amount is released. In case the application is made using the ASBA facility, the need for refunds is completely obviated. For example : if an investor makes an application for Rs. 2,00,000 , then in the earlier system, he was required to pay the entire sum of Rs. 2,00,000 upfront, either through a cheque or net-banking and then if shares worth Rs. 1,50,000 are only allotted, then Rs. 50,000 used to get refunded. Under the ASBA mechanism, the investor just need to keep Rs. 2,00,000 in his bank account and at the time of allotment only Rs. 1,50,000 would be debited to his account thus releasing the left over blocked amount of Rs. 50,000 and also doing away with the cumbersome task of issuing refunds.
13. Book Building Process : Book Building is one of the methods of carrying out a public issue, the other being the Fixed Price method. Under the Book Building method, the price at which securities will be offered is not known to the investor. The investor is allowed to bid in a given price range called the price band, and then, after the bids are closed & looking at the demand for the shares at various price levels within the price band, the final issue price is decided by the Merchant Bankers or BRLMs. This process leads to a better price and demand discovery. It is called the “Book Building Process” because during the entire issue period, the book for the offer remains open and keeps building up with the bids collected from investors.
14. BRLM (Book Running Lead Manager) : BRLM are those financial institutions whose names you find at the bottom of the bid-cum-application form like Karvy Securities, Kotak Mahindra, SBI Capital, Enam Securities etc. On a serious note, BRLMs or Merchant Bankers are those financial intermediaries which are involved in the IPO process right from the very first stage and play a vital role in preparation & submission of prospectus, price fixation, application processing, allotment and listing.
************************
The post Terms Used in an IPO first appeared on AmarParul Ventures (OPC) Pvt. Ltd.
]]>